The Definitive Guide to Ethical AI in Lending: From Compliance to Competitive Advantage
You’ve seen the potential. AI promises to revolutionize lending with unparalleled efficiency and accuracy. Yet, a nagging question remains: How do you innovate without inviting massive regulatory risk and eroding customer trust?
You’re not alone in this challenge. While 61% of financial institutions are already implementing or piloting AI, a staggering few—only 12.2%—have a well-defined and resourced AI strategy to govern it (Wolters Kluwer Q1 2026). This gap between ambition and governance is where risk thrives. Lenders are rightly concerned about fair lending, data privacy, and the “black box” problem, with regulatory concerns being a top-three hurdle to AI adoption.
This isn’t just about avoiding fines; it’s about building a resilient, future-proof lending operation. This guide moves beyond the high-level theory to provide the practical framework you need. We’ll break down how to build an ethical AI practice that not only meets regulatory demands but also becomes a powerful source of competitive advantage.
Decoding Fair Lending: Understanding and Mitigating Algorithmic Bias
The core promise of AI in lending is objective, data-driven decision-making. The reality is that AI models, trained on historical data, can inadvertently inherit and amplify human biases. This isn’t a theoretical risk; it’s a direct threat to Fair Lending compliance under regulations like the Equal Credit Opportunity Act (ECOA).
Bias can creep in through several avenues:
- Historical Bias: Data reflects past discriminatory lending patterns.
- Proxy Discrimination: A seemingly neutral variable (like ZIP code) strongly correlates with a protected characteristic (like race), effectively creating a proxy for discrimination.
- Data Quality Issues: Incomplete or inaccurate data for certain demographic groups can lead to skewed outcomes.
Regulators have made their position clear. The CFPB explicitly states there is “no special exemption for artificial intelligence” when it comes to compliance. This means you must be able to prove your models are fair. The first step is robust detection and mitigation. While many institutions struggle with this, you can implement a practical strategy focusing on Less Discriminatory Alternatives (LDAs) and continuous monitoring to ensure your models are not only powerful but also equitable.
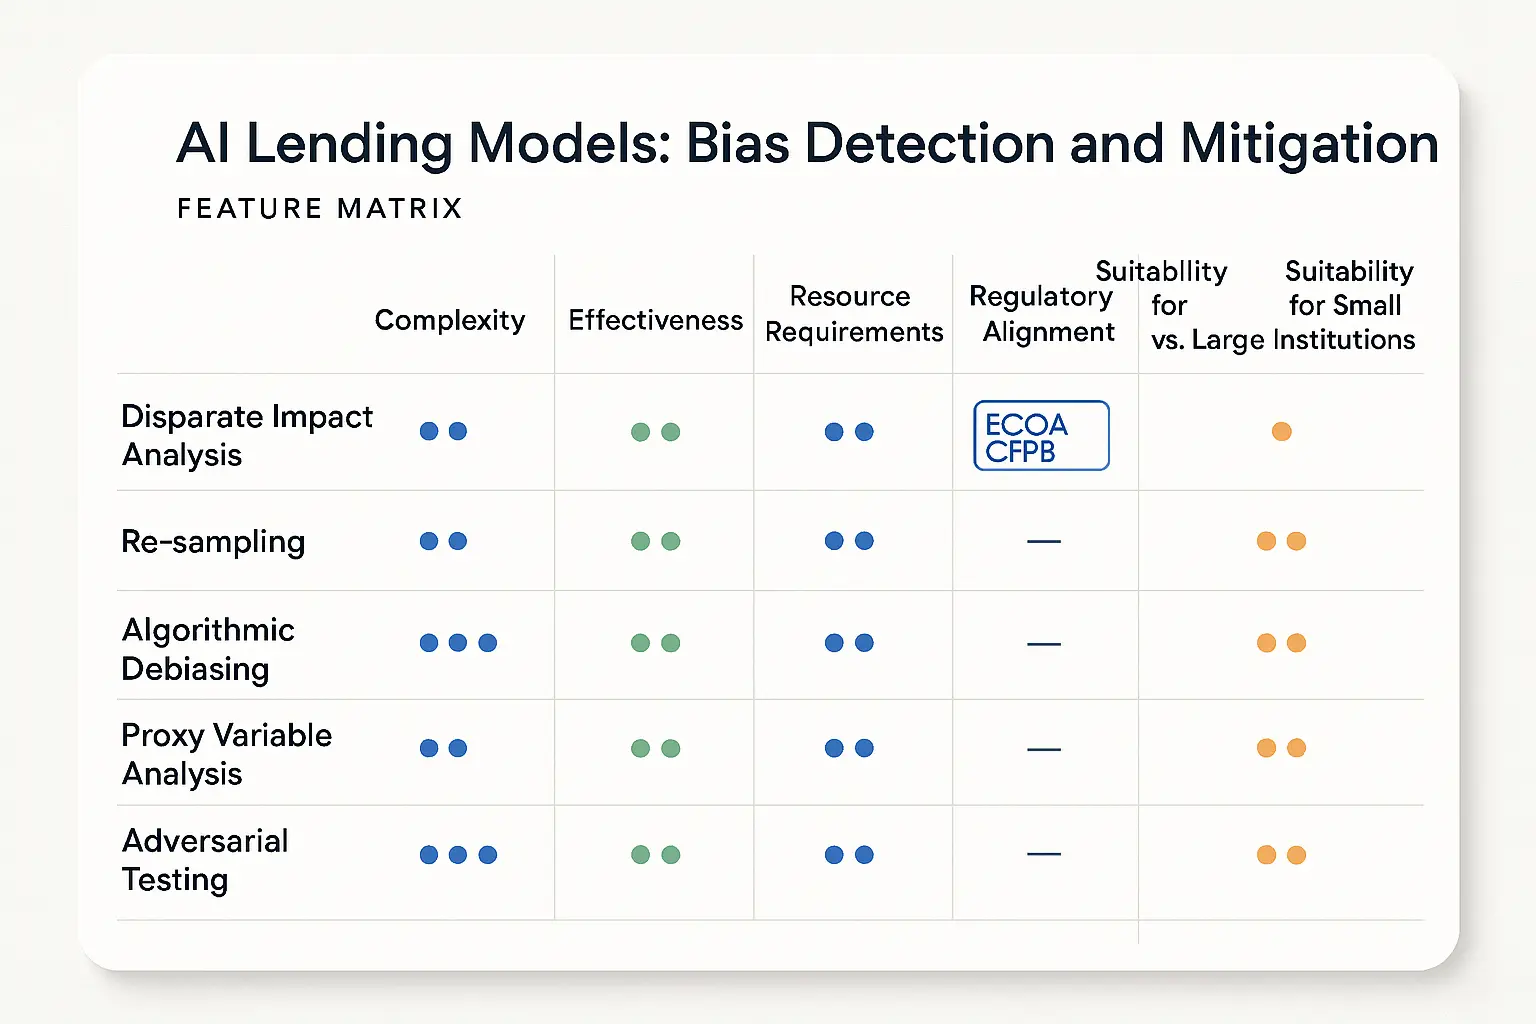
The goal isn’t to find a single “perfect” technique but to build a layered defense against bias. By combining proactive data analysis with post-deployment monitoring, you can create a powerful system for mitigating algorithmic bias that satisfies both regulators and customers.
Beyond the Black Box: Implementing Explainable AI (XAI) for Transparency
One of the biggest regulatory hurdles in AI-driven lending is explainability. When an AI model denies a credit application, the ECOA requires you to provide the applicant with specific, accurate reasons for the adverse action. Simply saying “the algorithm decided” is not a compliant response.
This is where Explainable AI (XAI) becomes essential. XAI comprises a set of tools and methods designed to make the decisions of complex models understandable to humans. It addresses what Deloitte calls the “black-box” problem, turning opaque predictions into transparent, auditable decisions.
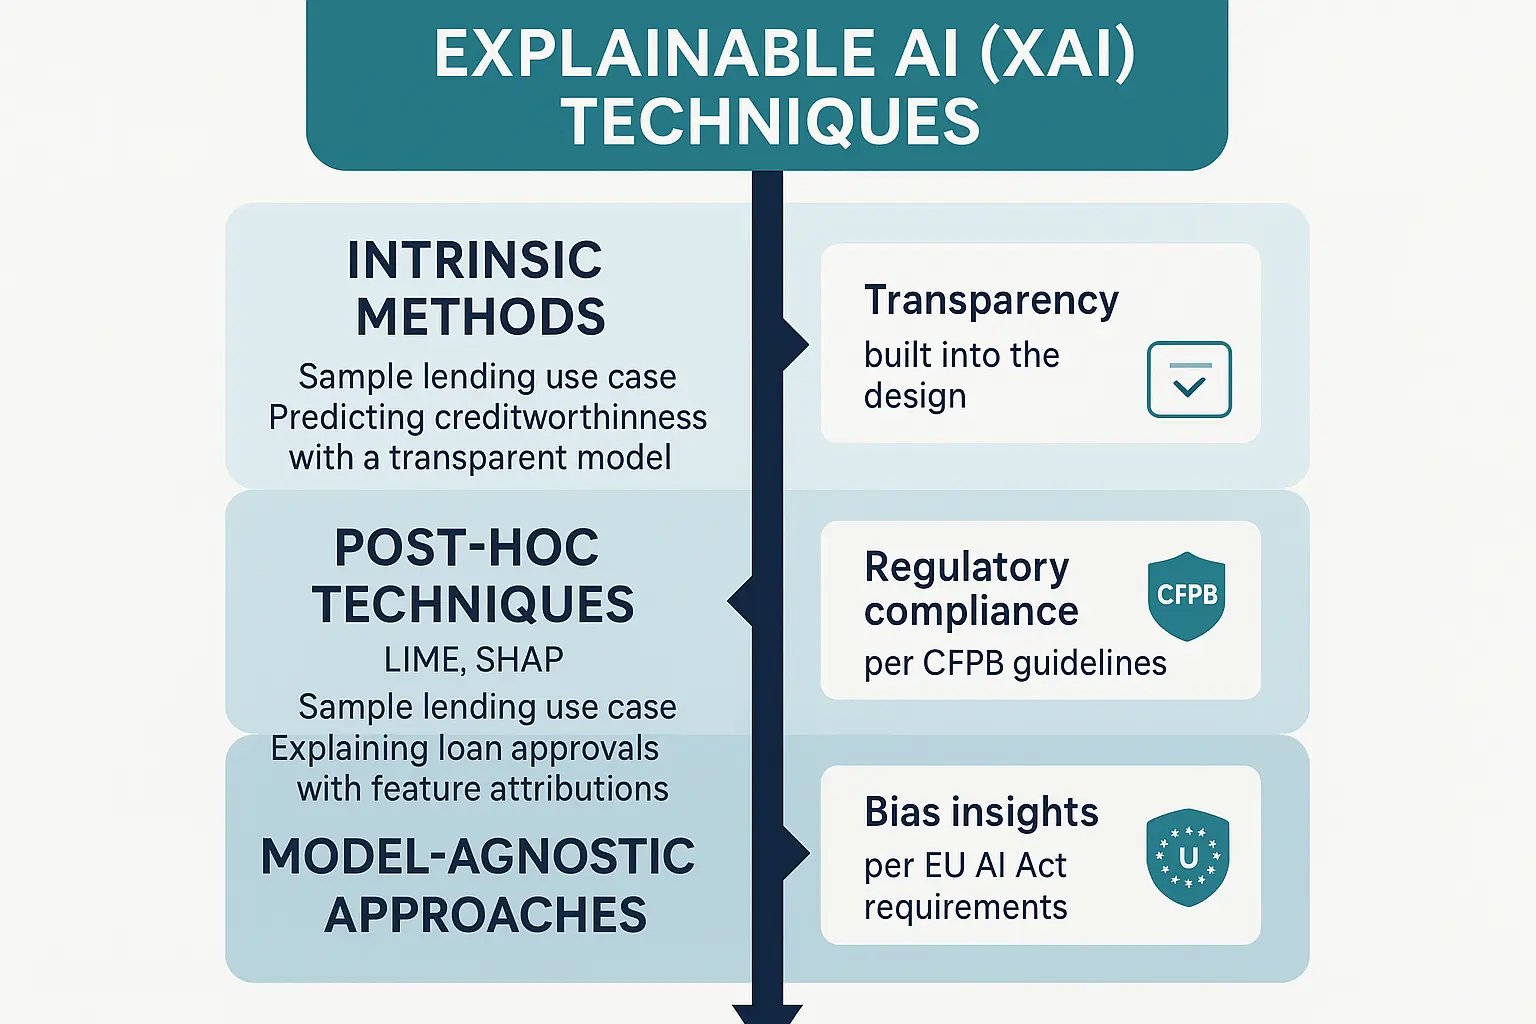
Key XAI methods include:
- LIME (Local Interpretable Model-agnostic Explanations): Explains individual predictions by showing how specific input features contributed to the outcome for that one applicant.
- SHAP (SHapley Additive exPlanations): A game theory-based approach that assigns an importance value to each feature for a particular prediction, offering a more holistic view of the model’s logic.
- Intrinsic Explainability: Using simpler, inherently transparent models like logistic regression or decision trees where the decision path is clear from the start.
Implementing XAI is now a primary concern for lenders, with 28% citing explainability and transparency as their top regulatory worry (Wolters Kluwer). An effective XAI strategy doesn’t just check a compliance box; it builds trust with customers by providing clear reasons for decisions and empowers your internal teams to validate and troubleshoot model behavior. Adopting one of the market-leading Explainable AI (XAI) solutions is no longer optional—it’s a core requirement for responsible lending.
Building a Resilient Foundation: Comprehensive AI Governance Frameworks
Technology alone won’t solve the ethical AI challenge. You need a comprehensive governance framework that embeds responsibility into your institution’s DNA. This is a significant area of vulnerability for the industry; currently, only 36% of institutions have established internal policies for ethical AI, and a mere 26% are confident their initiatives are aligned with regulations (Wolters Kluwer).
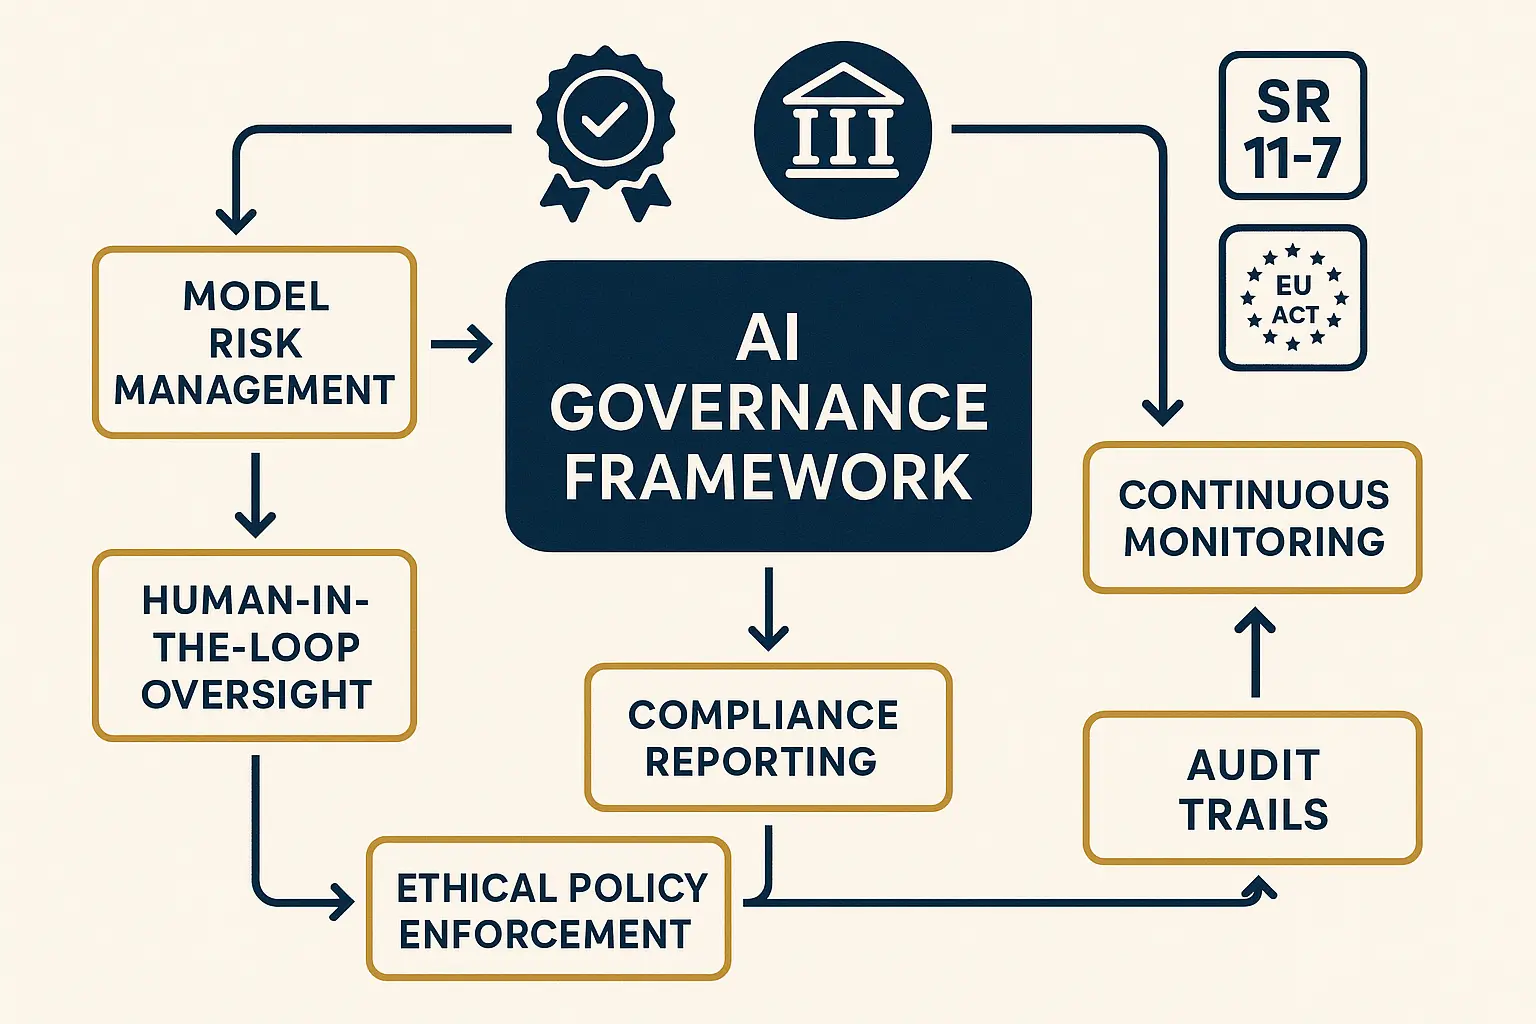
A robust AI governance framework is not a single document but a living system of people, processes, and technology. It should be built on the “three lines of defense” model familiar to any risk management professional and integrate principles from established guidelines like SR 11-7 and the emerging EU AI Act.
Key components of a successful framework include:
- AI Steering Committee: A cross-functional team (including business, risk, compliance, legal, and IT) to provide oversight and set the institution’s risk appetite for AI.
- Model Risk Management (MRM): Extending traditional MRM practices to AI, with rigorous validation, ongoing performance monitoring for drift and fairness, and comprehensive documentation.
- Defined Roles & Responsibilities: Clearly outlining who is accountable for model development, validation, deployment, and ethical oversight.
- Human-in-the-Loop (HITL): Establishing clear protocols for when human review and override are required, especially for high-stakes or borderline credit decisions.
- Comprehensive Audit Trails: Ensuring every automated decision can be traced, audited, and explained, both for internal review and regulatory requests.
Building a formal AI governance framework is the most critical step you can take to move from a reactive to a proactive stance on AI risk. It provides the structure needed to innovate safely and confidently.
The Practitioner’s Playbook: Step-by-Step Implementation
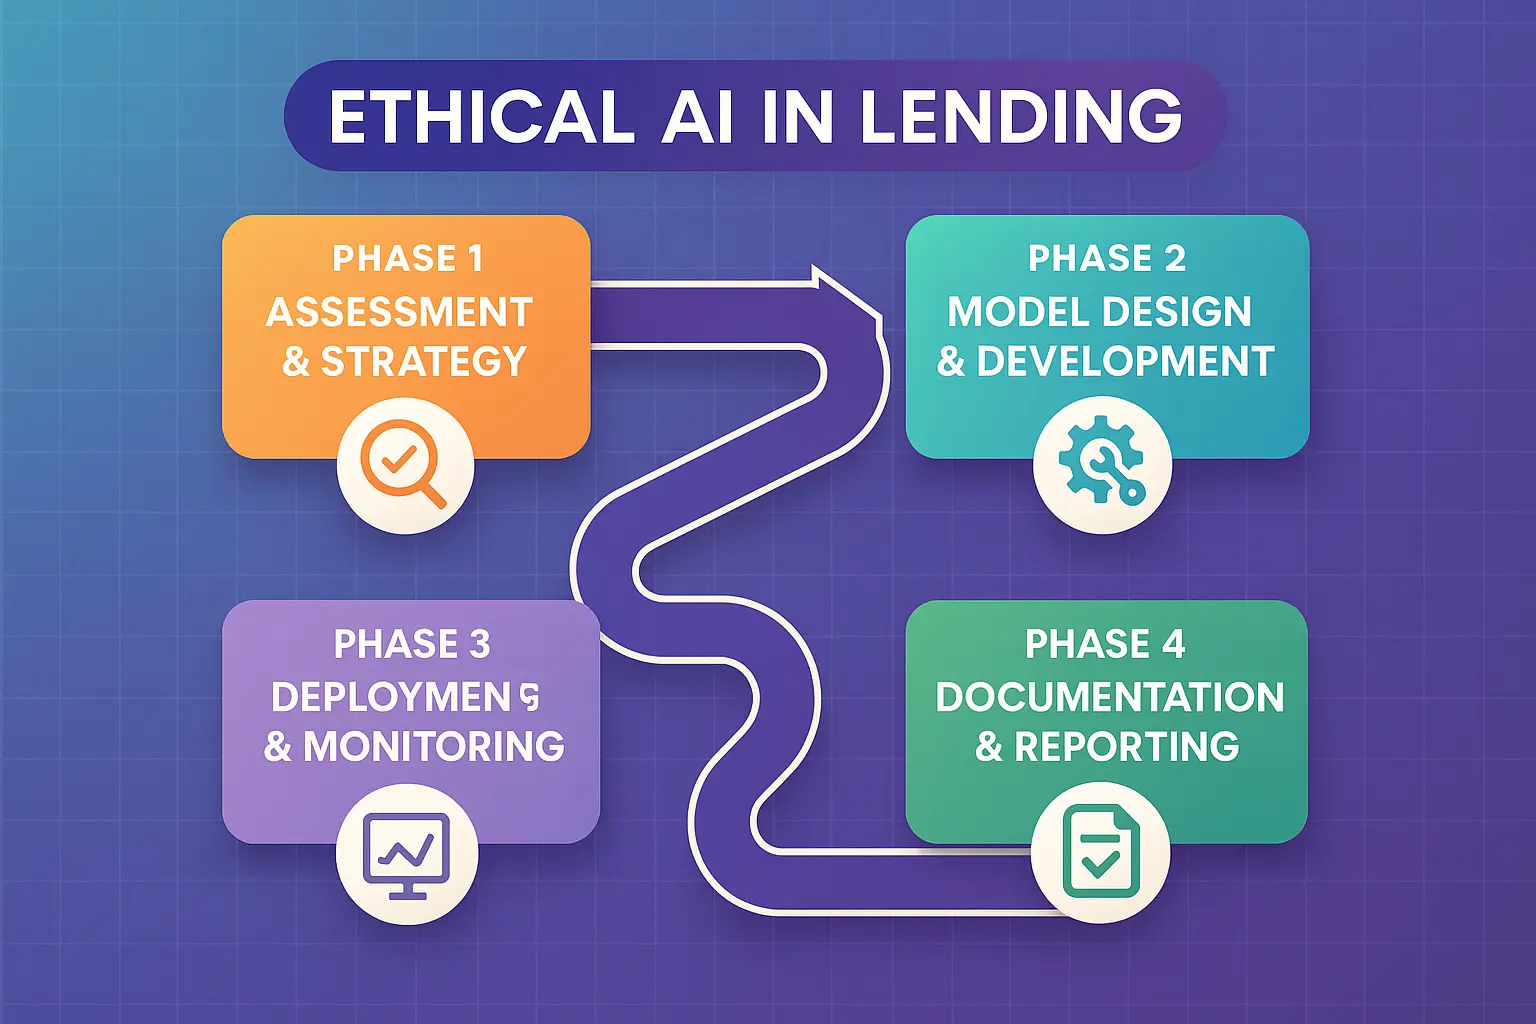
Moving from theory to practice requires a clear, phased approach. An effective implementation plan transforms abstract principles into concrete actions your teams can follow. While every institution’s journey is unique, it generally follows a four-stage process.
- Phase 1: Assessment & Strategy: Begin by assessing your organization’s AI maturity and defining your risk appetite. This involves identifying potential use cases, evaluating data readiness, and establishing clear ethical principles that will guide your AI development.
- Phase 2: Model Design & Development: Embed fairness checks and XAI techniques directly into the development lifecycle. This isn’t an afterthought; it’s a core part of building the model. This phase includes rigorous pre-deployment bias testing and validation against your established ethical principles.
- Phase 3: Deployment & Monitoring: Once a model is live, the work is not over. Implement continuous monitoring systems to detect model drift (degradation in performance) and fairness drift (changes in biased outcomes over time). Establish clear thresholds for when a model needs to be retrained or retired.
- Phase 4: Documentation & Reporting: Maintain meticulous documentation for every model, covering its purpose, data sources, training methodology, validation results, and fairness assessments. This documentation is your primary evidence of due diligence during regulatory audits.
This structured playbook ensures that ethical considerations are woven into every stage of the AI lifecycle, creating a repeatable and defensible process for responsible innovation.
Frequently Asked Questions (FAQ)
Q1: We are a smaller institution with limited resources. Isn’t this level of governance and compliance too expensive and complex for us?
This is a common and valid concern. The key is scalability. The principles of ethical AI—fairness, transparency, and accountability—are universal, but the implementation can be tailored to your size and complexity. Start with a foundational AI use policy and a streamlined governance committee. Leverage modern AI governance platforms that automate much of the monitoring and documentation, reducing the manual burden on your team. The cost of non-compliance, both in fines and reputational damage, far outweighs the investment in a scalable, right-sized governance program.
Q2: Will implementing fairness constraints on our AI models hurt their predictive accuracy and our bottom line?
There can be a slight trade-off between maximizing accuracy and ensuring fairness, but it’s often smaller than assumed and can be managed strategically. Many fairness-aware machine learning techniques are designed to minimize this trade-off. More importantly, this view misses the bigger picture. An ethical model can open up new, untapped markets of creditworthy individuals who were previously overlooked by biased legacy systems. Building trust with customers and regulators creates long-term franchise value that more than compensates for a marginal change in a single performance metric.
Q3: How can we keep up with AI regulations when they seem to be constantly changing?
Regulatory evolution is a certainty. This is precisely why a robust, adaptable governance framework is so critical. Instead of chasing every new headline, a strong framework founded on core principles (like those in the EU AI Act or NIST AI Risk Management Framework) will ensure you are well-prepared for future mandates. Focus on building systems for continuous monitoring, transparent documentation, and clear accountability. This proactive posture allows you to adapt to new rules from a position of strength, rather than scrambling to react.
Your Path to Confident AI Adoption
The challenges of implementing ethical AI in lending are significant, but they are not insurmountable. The data is clear: the industry is moving forward with AI, but a massive gap in strategy and governance has created unacceptable levels of risk.
Closing this gap is the single most important thing you can do to secure your institution’s future. By systematically addressing bias, embedding explainability, and building a comprehensive governance framework, you transform AI from a regulatory liability into a strategic asset. You move beyond mere compliance to build a more resilient, trustworthy, and profitable lending operation.
The time to act is now. Don’t let your institution be part of the 74% still struggling with regulatory alignment. Take the first step towards building a responsible AI practice that drives sustainable growth.